
Joshua Franks, Senior Vice President of Operations at e.l.f. Beauty Inc ELF, sold 5,512 shares of the company on September 1, 2026, according to a recent SEC Filing. Following the transaction, the insider now directly owns 138,797 shares of the cosmetics company.
The sale was executed at a price of $110 per share, representing a total transaction value of approximately $606,320. This disposition continues a notable trend for Joshua Franks, who has now sold 53,037 shares over the past year while making no corresponding purchases during that same period.
Insider Activity Context
The broader insider trading picture at e.l.f. Beauty Inc reveals a significant imbalance between buying and selling activity. Over the trailing twelve months, the company has recorded just 1 insider buy transaction, contrasted sharply with 37 insider sell transactions. This pattern typically signals that those with the most intimate knowledge of the company’s operations and future prospects are choosing to reduce their exposure, which can sometimes be interpreted as a cautionary signal for prospective investors.
However, it is important to contextualize this activity. Insider selling can occur for a variety of reasons unrelated to a bearish outlook on the company, including portfolio diversification, tax planning, or funding personal expenditures. The sheer volume of selling relative to buying, however, does warrant attention from shareholders and potential investors alike.
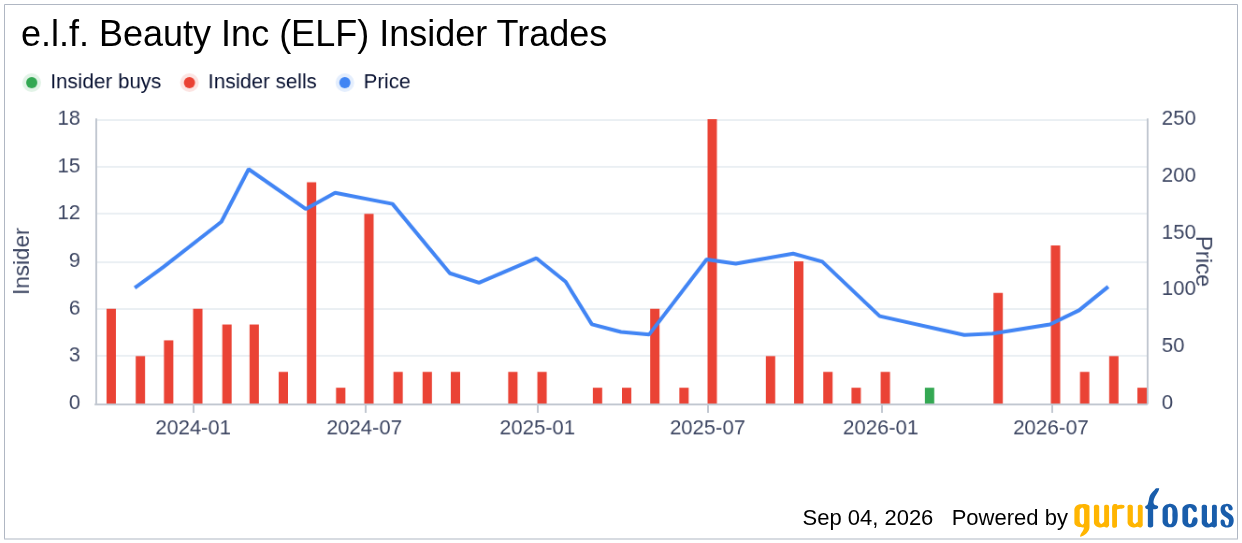
The insider transaction history chart above illustrates the persistent selling pressure from company insiders throughout the past year. With only a single buy transaction against nearly four dozen sells, the insider sentiment at e.l.f. Beauty Inc currently skews heavily toward distribution rather than accumulation.
Company Overview
e.l.f. Beauty Inc is a multi-brand beauty company that offers cosmetically elegant, high-quality, prestige-inspired products at accessible price points. The company’s portfolio includes its flagship e.l.f. Cosmetics brand, along with e.l.f. Skin, and the recently acquired Naturium and Mighty Patch brands. e.l.f. Beauty distributes its products primarily through national retailers, e-commerce platforms, and international distributors, with a strong emphasis on digital marketing and social media engagement to drive brand awareness and consumer loyalty. The company has carved out a distinctive niche in the beauty industry by combining value pricing with trend-forward product development, appealing particularly to younger, digitally-native consumers.
Valuation Analysis
At the time of the insider’s recent sale, shares of e.l.f. Beauty Inc were trading at $110 apiece, giving the company a market cap of approximately $6.34 billion. This valuation places the company firmly in the large-cap growth category within the consumer staples sector.
From a traditional earnings perspective, the stock appears richly valued. The current price-earnings ratio stands at 109.60, which is substantially higher than the industry median of 16.07 and also exceeds the company’s own historical median price-earnings ratio. This elevated multiple suggests that investors are pricing in significant future earnings growth, reflecting the company’s impressive revenue trajectory and brand momentum in recent years.
Similarly, other valuation metrics paint a picture of a growth-oriented stock trading at a premium. The price-sales ratio and price-book ratio are both elevated relative to historical norms, while the price-to-free cash flow multiple also reflects the market’s willingness to pay a premium for the company’s cash generation capabilities and expansion prospects.

Despite these rich earnings multiples, GuruFocus’s proprietary valuation metric tells a different story. The GF Value for e.l.f. Beauty Inc is calculated at $169.89, which stands significantly above the current trading price of $110. This implies a price-to-GF-Value ratio of 0.65, placing the stock in the “Significantly Undervalued” category according to GuruFocus’s assessment framework.
For context, the GF Value represents GuruFocus’s estimate of the stock’s fair intrinsic value. This calculation incorporates three primary factors: historical trading multiples (including price-earnings, price-sales, price-book, and price-to-free cash flow ratios), a GuruFocus adjustment factor based on the company’s past operational returns and growth trajectory, and forward-looking business performance estimates provided by Morningstar analysts. When the market price falls substantially below this calculated intrinsic value, as is currently the case with e.l.f. Beauty, the stock may present a compelling opportunity for value-oriented investors who believe the underlying business fundamentals will ultimately be reflected in the share price.
Guru Ownership Trends
Beyond insider activity, institutional sentiment as tracked by GuruFocus provides additional context for investors monitoring e.l.f. Beauty Inc. Currently, 5 gurus hold positions in the company’s stock, with 3 of these prominent investors having added to their positions in recent quarters while 5 trimmed their holdings. This premium 13F ownership data, which GuruFocus tracks meticulously, offers a window into how sophisticated institutional money managers are positioning themselves relative to the stock.
The mixed signals from guru investors—with some adding and others reducing—suggest a divergence of opinion among professional money managers regarding the company’s near-term prospects. This stands in contrast to the more uniformly bearish signal emanating from insider selling activity.
Interpreting the Combined Signals
When evaluating the insider sale alongside the valuation picture, a nuanced narrative emerges. On one hand, the persistent insider selling could be interpreted as a lack of confidence in the stock’s near-term appreciation potential from those closest to the business operations. On the other hand, the GF Value assessment suggesting the stock is significantly undervalued implies that the market may have already priced in considerable pessimism or growth concerns.
For investors, this combination of signals—heavy insider selling against a backdrop of apparent undervaluation—creates an interesting tension. The insider activity may reflect concerns about specific operational challenges or competitive pressures that are not yet fully apparent in public financial disclosures. Alternatively, insiders may simply be taking profits after a period of substantial stock appreciation, with the current valuation potentially representing an attractive entry point for long-term investors who believe in the company’s growth story.
As always, investors should conduct their own thorough due diligence, considering both the quantitative signals from insider transactions and valuation metrics alongside qualitative factors such as brand strength, competitive positioning, and management’s strategic execution capabilities. The beauty industry remains highly competitive, and e.l.f. Beauty’s ability to maintain its growth trajectory while navigating evolving consumer preferences will ultimately determine whether the current valuation discount represents a genuine opportunity or a value trap.
This stock alert was generated using automated technology and GuruFocus financial data to provide readers with timely and accurate market reporting. This content was reviewed by GuruFocus editorial team prior to publication. Please send any questions or comments about this story to [email protected].